|
Getting your Trinity Audio player ready...
|
CBN Mops Up N3.3tn From Banks as Investors Show Strong Demand for 182-Day OMO Bills
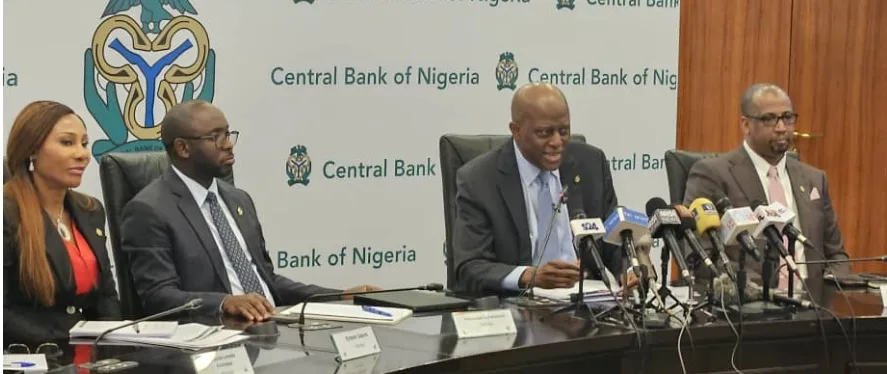
The Central Bank of Nigeria allotted N3.309 trillion in Open Market Operations (OMO) bills at its auction on October 6, after investors submitted bids worth N3.511 trillion against the N2 trillion initially offered. The allotment was about 165 percent of the planned size. It shows how much appetite there is for short-term government paper, and how willing the central bank is to take in more than it first signalled when cash is plentiful.
The auction covered two maturities. The 182-day bill took the bulk of the money, with N2.671 trillion allotted at a stop rate of 16.92 percent, or about 81 percent of the total. The 147-day bill drew N637.2 billion at a stop rate of 17.22 percent. Put simply, the shorter bill paid investors about 30 basis points more, and they still chose the longer one in much larger numbers. That is the clearest signal in the results.
Why would buyers accept slightly less yield for an extra five weeks of lock-in? The central bank does not explain individual bids, so what follows is reasoning from the numbers rather than confirmed fact. The most likely explanation is the direction of interest rates. The policy rate was cut by 350 basis points to 23 percent on September 22, and the corridor around it was narrowed. Investors who expect yields to keep drifting lower have a reason to lock in current levels for as long as the tenor allows, because a 182-day bill bought now continues paying 16.92 percent even if new bills are priced lower in December. A longer bill also reduces the effort and uncertainty of reinvesting every few weeks.
Return relative to inflation also helps. Headline inflation was 15.39 percent in August. Stop rates on these bills are normally quoted as discount rates, so the effective return is somewhat higher than the headline figure. Either way, investors are earning above the pace of price increases, which keeps the paper attractive. By comparison, the 364-day Treasury bill cleared at 15.85 percent at the auction held the following day, so OMO bills are paying more for shorter maturities. That gap helps explain the strength of the bids, although access matters as well. OMO auctions have generally been open to a narrower group of investors than Treasury bill sales, which means the pool of buyers is smaller but includes banks with large cash balances to place.
Those balances are the other side of the story. Banks hold large amounts of surplus naira, and the central bank wants to prevent that cash from fuelling price pressures. The OMO auction is one of its main tools. By issuing bills and collecting naira, the CBN takes money out of the banking system and holds it until the bills mature. A bank that buys a bill swaps cash it could otherwise lend or deposit overnight for a fixed-return asset it cannot easily spend.
The headline figure overstates how much cash left the system. About N2.17 trillion in earlier OMO bills matured around the same time and returned to banks, so the net withdrawal came to roughly N1.14 trillion. That is still a meaningful tightening, and it matches the broader pattern in September, when the CBN sold about N17.51 trillion in OMO bills against N10.89 trillion in maturities, a net withdrawal of around N6.62 trillion. The auction on September 29 stood out, with N4.69 trillion allotted against N2.43 trillion in maturities. The latest sale is smaller than that peak, but it continues the same approach of taking back more than it returns.
The effects were visible quickly. Banks cut their overnight placements at the CBN’s Standing Deposit Facility by N941.85 billion in a day, leaving N3.76 trillion. Market reports also said the average cost of short-term funding rose by 32 basis points to 20.59 percent. That is the intended result of an auction like this. When the central bank soaks up cash, banks that were comfortable lending to each other at the floor of the rate corridor have to compete a little harder for funds, and rates edge up. The aim is to keep money market pricing close to the new 23 percent policy rate and prevent excess cash from pushing it down to the 20 percent floor and below.
The effect on the wider financial market is likely to be gradual. The Treasury bill auction on October 7 shows that demand for government debt is not limited to OMO. The central bank offered N900 billion on behalf of the Federal Government, received subscriptions of N1.77 trillion and allotted N968.47 billion. Investors put N1.68 trillion into the 364-day bill alone, which suggests they want longer maturities across the board. If that continues, the government can fund itself at lower cost, because heavy demand pushes stop rates down. A fall in the one-year bill rate to 15.85 percent is already a step in that direction.
For banks, the trade-off is between safety and lending. Government paper pays well and carries almost no risk, and with reserve requirements at 45 percent for commercial banks, the room left for loans is limited. Unless borrowers offer returns that justify the risk, lenders have little reason to move away from bills. That is a concern for businesses hoping to see cheaper credit after the rate cut. The policy rate has fallen, but loan pricing depends on what banks can earn elsewhere, and bills at 17 percent set a high bar for new lending.
The bond and equity markets could also feel the effects. If yields on short-term bills fall further, some investors may move into longer-dated bonds to find better returns, which would support bond prices. Lower yields on safe assets can also make shares more attractive to investors seeking income, although stock prices respond to company earnings and general sentiment as much as to interest rates. The naira is another point of connection. Foreign investors who buy naira-denominated bills must convert dollars first, so strong demand for OMO paper can add to dollar supply at the foreign exchange market. The currency has traded near N1,333 per dollar this week, and turnover at the NFEM topped $1 billion on October 6.
The next test arrives this month. About N9.05 trillion in OMO bills is due to mature in October, roughly 68 percent of projected inflows to the system. That much cash returning to banks and investors will need to be reabsorbed, either through new auctions or by flowing into other assets. If the CBN offers less than what matures, liquidity will build quickly and rates could slip. If it keeps allotting above the offer size, as it did this week, the tightening effect will continue. Market participants will therefore be reading each weekly auction for hints about how the central bank intends to manage the rest of the month.
The next policy meeting is scheduled for November 23 and 24. Until then, auction results will be the best guide to how comfortable the CBN is with current liquidity, and how long investors are willing to wait for yields to fall. Readers who follow banking and markets can find more coverage on Business Tech.