|
Getting your Trinity Audio player ready...
|
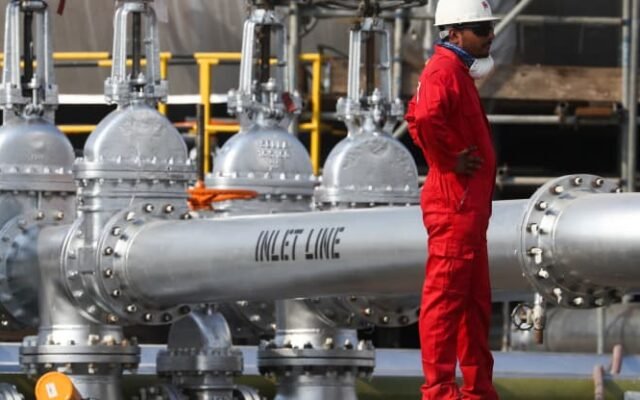
Crude oil got a little cheaper this week because the barrels that vanished from the market during the Iran war are returning. Brent futures finished Monday at 100.32 dollars, a fall of about 2 percent, and then hovered near 100.7 dollars in early Asian trading on Tuesday. That is a modest retreat from the highs of recent weeks, and it still leaves the global benchmark well above where it sat a few months ago.
The cause of the softer tone is easy to identify. Banks and tanker trackers have spent days reporting that Middle East exports are close to what they were before hostilities began. JPMorgan estimates that regional crude shipments, averaged over ten days, have reached 17.5 million barrels a day, which is 98 percent of the pre-war rate. Goldman Sachs is more generous still. Its figure of 23.3 million barrels a day matches the average for all of 2025. The two banks count cargoes differently, so the numbers do not line up exactly, but neither suggests the market is still starved of Gulf oil.
Ship-tracking data from Kpler adds detail on the Strait of Hormuz itself. Crude passing through the waterway averaged 13.5 million barrels a day over the seven days to last Monday, the same as the baseline before the war. That matters because roughly a fifth of the world’s oil trade normally travels this route, and its near-closure earlier in the conflict triggered an energy shock felt from Asian refineries to African fuel importers.
Some of the recovery owes less to the strait than to the ways around it. About 40 percent of crude leaving the Gulf now avoids Hormuz entirely, up from 17 percent before the war. Saudi Arabia has pushed more oil through its pipeline to the Red Sea, other exporters have used ship-to-ship transfers and shuttle vessels, and a two-way lane along the Omani coast, protected with American naval support, has let convoys run again. The result is a supply chain with more exits than it had in February, which should make the next scare less punishing than the last one.
There are also signs that producers want their customers back. Saudi Aramco lowered its November price for Arab Light sold to Asia to 5 dollars below the regional reference, after offering a 2 dollar discount for October. Deeper discounts from the biggest exporter usually mean it expects ample supply and wants to hold its share of the market. Add the latest emergency stock release by G7 countries, and the supply side looks easier than it did a month ago.
The cheerful numbers have limits, and the first is fuel. Refined products leaving through Hormuz averaged only 677,000 barrels a day, compared with 3.6 million before the war. When crude and products are combined, Kpler counts 14.2 million barrels a day, about 80 percent of the strait’s normal 17 million. Damaged refining capacity and disrupted shipping are keeping diesel scarce, and prices for it are at or near records. China has suspended its October fuel exports, which tightens things further for buyers who rely on Asian cargoes. Households and firms generally feel diesel before they feel Brent, so the relief on the crude screen can be slow to reach them.
The second limit is the gap between paper and physical markets. Dated Brent, which prices cargoes that are really changing hands, has climbed above 120 dollars even while the futures contract sat near 101. Buyers needing oil quickly are paying a steep extra amount for it, reflecting higher costs for freight, insurance and guaranteed delivery. In plain terms, the headline price flatters how comfortable the market actually is.
Security is the third. A fourth tanker has reportedly been struck in or around Hormuz in recent days, and there have been reports of Houthi attacks on Saudi energy assets and Iranian strikes on shipping. Traders are reacting to each development sharply. Brent rose about 8.6 percent on September 24 and gave back about 7.3 percent the following session. Moves of that size show a market that has not stopped bracing for the next disruption.
One large supplier is still missing. Iranian crude exports through the strait are close to zero under the US naval blockade, so the recovery so far has come entirely from Iran’s neighbours. If the blockade were relaxed, more oil could reach buyers and add to downward pressure. If the conflict escalated again, the opposite could occur, and spare supply elsewhere would be tested.
Looking back at the year helps put 100 dollars in context. Brent leapt to around 80 to 82 dollars in early March as the war began, then drifted to near 70 dollars by July as the market adjusted. Today’s price is therefore some 30 dollars above the summer low even though crude volumes have largely normalised. What is being priced in is no longer a shortage of crude. It is the shortage of diesel and other products, the cost of moving oil safely, and the chance that another strike closes a channel that is open today.
For exporters, elevated prices bring welcome revenue, though a swift reversal would hurt budgets built on high assumptions. For import-dependent economies, including fuel buyers in Nigeria, cheaper crude does not translate to cheaper petrol or diesel automatically. Refining margins, shipping costs and currency movements all sit between the oil well and the filling station. Governments weighing subsidies, central banks watching imported inflation and companies planning transport budgets will be tracking tanker traffic, product exports and security headlines. Readers following how energy costs shape business and technology decisions can find related reporting at Business Tech.
The near-term direction favours buyers. Crude is flowing, Gulf producers are discounting and strategic reserves are being tapped. What remains uncertain is whether the 100 dollar mark can hold if the waterway stays quiet and refined fuel finally catches up with crude. Answering that will depend less on forecasts than on whether the next few weeks pass without another vessel being hit.