|
Getting your Trinity Audio player ready...
|
US government’s weekly oil report told a story that now feels like it belongs to another market. For the week ending October 3, 2026, the Energy Information Administration (EIA) reported that commercial crude inventories rose by 3.7 million barrels, more than analysts expected, while total petroleum products supplied climbed to 21.990 million barrels per day, described in the figures cited as the highest level since December 2022. The EIA’s own archive confirms that it published a weekly report covering that period on October 8, 2026. This article treats the headline numbers as the figures supplied for that report, and it sets them against the very different data released this week.
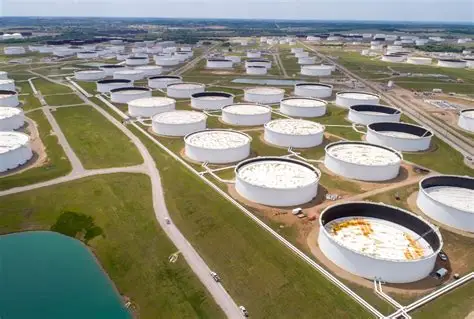
Start with what a crude build and strong demand meant at the time. When inventories rise more than forecast, traders usually read it as a sign that supply is outrunning what refiners need, which tends to weigh on prices. Strong product demand pulls the other way, because it suggests consumers are buying fuel in large quantities. The EIA’s total products supplied number is a proxy for consumption, measuring what leaves the primary supply system for the market, and it can swing from week to week for technical reasons. A reading near 22 million barrels per day is high by recent standards, so the October 2026 report was a mixed signal: more oil in tanks, but also more fuel going out the door.
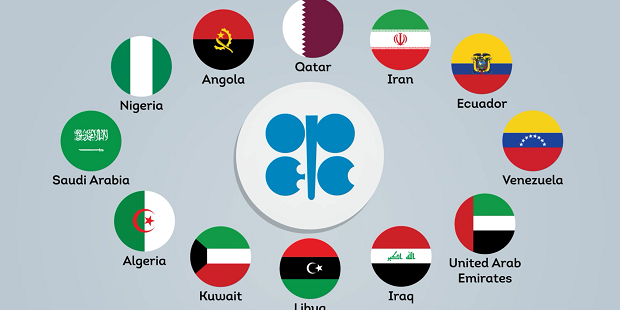
The surrounding market explains why the build mattered. In early October 2026, oil was cheap relative to today. Fortune’s price tracker shows Brent at about $66 a barrel a year before this week, and the global conversation was about oversupply. Gulf News reported that OPEC+ had just agreed to raise output by 137,000 barrels per day from November, another step in unwinding voluntary cuts as the group worked to recover market share. The same report said the International Energy Agency expected global inventories to rise sharply in the final quarter of 2025 and warned that a record surplus could emerge in 2026 as demand cooled and output across the Americas surged. Against that forecast, a 3.7 million barrel US build fit the narrative of a market filling up.
That narrative did not survive. The US-Israeli war on Iran began on February 28, 2026, according to Reuters reporting carried by Nation Thailand, and the disruption around the Strait of Hormuz has restricted crude supplies and lifted energy costs ever since. Brent now trades around $100 to $104, roughly 50 percent above where it stood a year ago, and West Texas Intermediate is near $91. The 2026 surplus that agencies once feared has been replaced by a scramble for barrels, with governments releasing emergency stocks and producers pumping well below their targets. OPEC+ itself has shifted from adding barrels to pausing, holding its November 2026 targets unchanged at its October 4 meeting.
The latest weekly figures show how far the picture has moved. The EIA reported on Wednesday that US commercial crude inventories fell by 3.2 million barrels to 424.1 million in the week ended October 2, 2026, when a Reuters poll had pointed to a build of about 1.7 million. Gasoline stocks rose by 400,000 barrels to 204.7 million, and distillate stockpiles, including diesel, were roughly unchanged at 105.1 million barrels, about 12 percent below their five-year average. Refinery utilization stood at 92.7 percent. In other words, the same report that delivered a surprise build twelve months ago has now delivered a surprise draw, with a market that is much tighter in the fuel that matters most for freight and heating.
Demand tells a quieter but still interesting story. Over the last four weeks, total products supplied averaged 21.1 million barrels per day, up 0.7 percent from a year earlier, according to oilprice.com’s summary of this week’s data. That is below the single-week 21.990 million figure from October 2025, which is a reminder that weekly and four-week numbers are different measures and should not be compared carelessly. A single strong week can lift the headline, while a four-week average smooths out noise. Even so, the comparison suggests that US consumption has not collapsed under triple-digit crude, even if it is not surging either. Gasoline demand averaged 8.8 million barrels per day and distillate demand 3.8 million barrels per day, the latter down 1.6 percent year over year.
The policy backdrop has changed as dramatically as the price. A year ago, the Strategic Petroleum Reserve was a background statistic. This week, API data shows another 800,000 barrels left the reserve, bringing it to about 283 million barrels, with exchanges of 40 million barrels announced on September 29. A tracking site reports that the G7 agreed on October 2 to release 100 million barrels of diesel and crude from strategic stocks through the IEA, though that figure should be treated as reported rather than confirmed. A government drawing on emergency supplies is a world away from the oversupplied market that analysts described in autumn 2025.
There are practical lessons here for anyone who follows oil data. First, weekly inventory numbers are best read against expectations and context. A build in a market worried about surplus is bearish, while a build in a market short of supply may be absorbed without much impact. Second, forecasts of surplus or shortage can be overturned quickly by geopolitical events, as the past eight months have shown. Third, the details beneath the headline, such as refinery runs, imports, exports and product stocks, often matter more than the crude figure alone. A diesel stockpile that sits well below average, as it does now, is a more urgent concern for businesses than a crude barrel count.
For readers outside the United States, including in Nigeria, the weekly EIA report matters because it influences benchmark prices that determine export revenue for producers and import costs for refined fuel. Nigeria’s regulator reported crude and condensate output of about 1.68 million barrels a day in August, so the benefit of higher prices depends on keeping barrels flowing. The EIA publishes the complete tables each Wednesday in its Weekly Petroleum Status Report, and OPEC+ decisions are posted on the OPEC site.
Readers who follow global energy, markets and technology can find more coverage at BusinessTech Nigeria. The October 2025 report is a useful marker of how fast sentiment can change: a year ago, the debate was how big the glut would be, and today it is how long the squeeze will last.