|
Getting your Trinity Audio player ready...
|
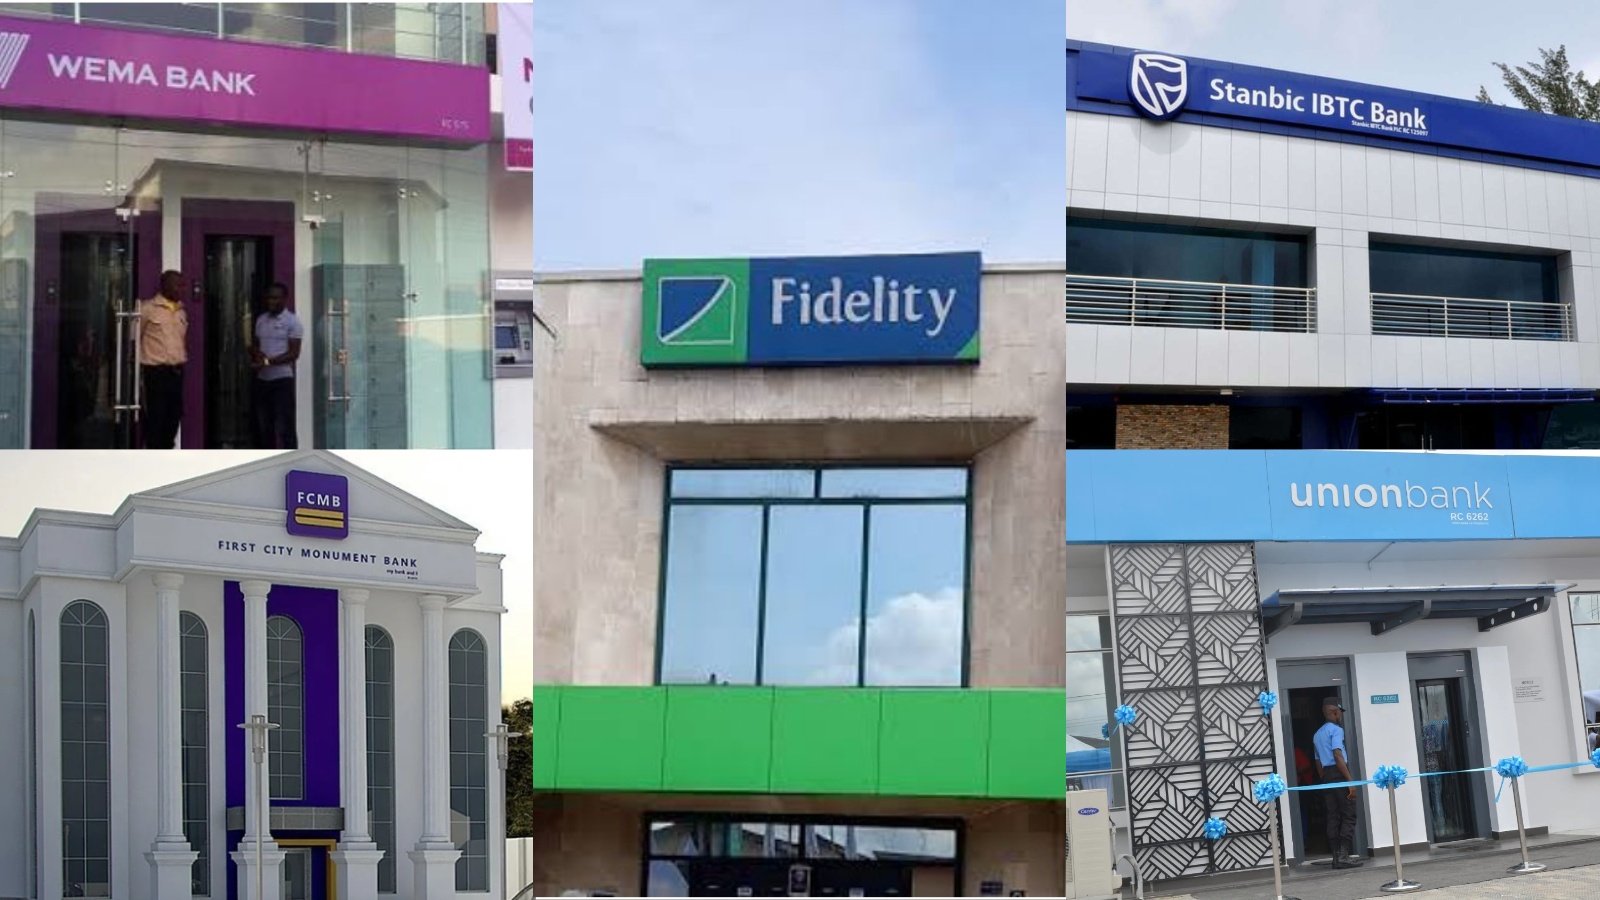
Nigeria’s banking sector has raised ₦4.65 trillion in fresh capital through the Central Bank of Nigeria’s CBN recapitalisation exercise, a development that strengthens the industry’s financial base and raises expectations for increased lending, improved resilience and stronger support for businesses across the country.
CBN Governor Olayemi Cardoso disclosed the figures following Nigeria’s participation in the 2026 Annual Meetings of the International Monetary Fund and World Bank Group in Bangkok, Thailand. According to the governor, domestic investors contributed slightly more than 20 per cent of the capital raised, indicating that local investors participated in an exercise widely viewed as important to the future capacity of Nigeria’s financial system.
The disclosure comes as Nigerian banks prepare to operate under stronger capital requirements and respond to an economy in which businesses continue to seek financing, households face borrowing costs, and policymakers are working to sustain lower inflation.
The recapitalisation programme has been one of the most significant regulatory changes affecting Nigerian lenders in recent years. Its central objective is to ensure that banks maintain sufficient capital to support their operations, withstand financial shocks and finance larger transactions without exposing depositors and the wider economy to unnecessary risks.
For customers, businesses and investors, however, the significance of the ₦4.65 trillion figure will depend on what banks do with their strengthened balance sheets. Raising capital can improve a bank’s ability to absorb losses and expand its lending capacity, but it does not automatically guarantee cheaper loans, easier access to credit or better customer service.
The next stage will therefore test whether the additional capital can translate into measurable economic benefits.
The recapitalisation exercise was introduced by the CBN to strengthen the banking industry and ensure that financial institutions have capital levels that reflect the scale and complexity of their activities. The regulator announced the revised minimum capital requirements in March 2024, giving banks a transition period to meet the new standards.
The requirements vary according to the type of banking licence held by each institution. International commercial banks face a higher minimum capital threshold than national and regional commercial banks, while specialised institutions operate under requirements appropriate to their licences.
The policy has encouraged banks to explore different ways of strengthening their capital positions, including public offers, rights issues, private placements, retained earnings and other approved capital-raising arrangements.
For the banking industry, the exercise represents more than a regulatory compliance process. It is also a test of investor confidence, management strategy and the ability of financial institutions to position themselves for a changing economic environment.
Cardoso’s latest disclosure provides an indication of the scale of the capital raised across the sector. It also places renewed attention on the role of Nigerian investors in supporting the financial system, even as banks seek capital from international markets and other funding sources.
The fact that domestic investors contributed slightly more than one-fifth of the total suggests that local participation formed a meaningful part of the exercise. However, the figure should not be interpreted as evidence that all the remaining capital came from foreign investors, since the reported information does not provide a complete breakdown of every source of funding.
The distinction matters because a clear understanding of capital ownership can help investors assess the changing structure of the banking sector. It can also provide regulators and market participants with a better picture of how Nigerian financial institutions are financing their growth.
For shareholders, recapitalisation can create opportunities as well as challenges. Banks that successfully raise capital may be better positioned to expand their operations, invest in technology, pursue larger corporate customers and strengthen their capacity to manage financial risks.
At the same time, issuing additional shares can dilute the ownership percentage of existing shareholders who do not participate in a capital-raising exercise. The effect on individual investors depends on the terms of the offer, the price at which new shares are issued and the bank’s subsequent financial performance.
Investors will also want to know whether stronger capital positions eventually translate into higher earnings. The answer will depend on loan growth, the cost of deposits, operating expenses, credit losses and the overall performance of the Nigerian economy.
A bank can have a stronger capital base and still face pressure on profitability if borrowers struggle to repay loans or if funding and operating costs remain elevated.
For businesses, the potential benefits could be more direct, particularly if banks use their stronger balance sheets to extend productive credit. Manufacturers, agricultural enterprises, exporters, construction companies and small businesses frequently require financing to purchase equipment, maintain inventories, expand production and meet operating expenses.
Access to suitable financing can determine whether a company expands its workforce, introduces new products or postpones an investment. Stronger banks could, in principle, support more of these activities, provided that lending decisions are based on sound risk assessments and that viable borrowers can meet the conditions attached to credit facilities.
Nevertheless, recapitalisation alone cannot resolve every challenge affecting business lending in Nigeria.
Banks must still consider the ability of borrowers to repay, the quality of available collateral, the stability of business revenues and the broader economic outlook. Small enterprises without formal financial records may continue to struggle to obtain loans even when lenders have substantial capital.
The cost of borrowing also remains important. A stronger banking system does not necessarily mean that commercial lending rates will fall immediately, because interest rates reflect monetary policy, inflation expectations, funding costs, credit risks and other market conditions.
The CBN has also reported progress on some of Nigeria’s broader economic indicators. In comments reported after the IMF and World Bank meetings, Cardoso said headline inflation declined to 14.63 per cent in September 2026. He also reported that Nigeria’s external reserves had risen above $55 billion, while formal remittance inflows were approaching $1 billion monthly.
These figures provide additional context for the banking sector’s outlook, although they do not establish that recapitalisation itself caused the changes in inflation or foreign reserves.
Lower inflation, if sustained, could improve the ability of households and businesses to plan their spending. Stronger external reserves can also help support confidence in the country’s capacity to meet external obligations and manage pressures on the foreign exchange market.
For banks, the broader economic environment influences the quality of their loan portfolios, the value of their investments and the ability of customers to meet repayment obligations.
The governor also said Nigeria’s sovereign outlook had been revised from stable to positive by Fitch Ratings. Such an outlook revision can signal an improvement in the rating agency’s assessment of a country’s prospects, but it is not the same as a sovereign credit-rating upgrade and does not remove existing economic risks.
Taken together, the developments highlight the relationship between banking stability and the wider economy. Banks need sufficient capital to withstand losses, while a healthy economy provides borrowers with better opportunities to generate revenue and repay loans.
Regulators must also maintain an appropriate balance between financial stability and economic activity. Requirements that are too weak can leave banks vulnerable to unexpected losses, while restrictions that unnecessarily constrain lending can limit the flow of credit to productive sectors.
The CBN’s recapitalisation programme is intended to improve the first part of that balance by strengthening the financial foundations of the banking system. The effectiveness of the policy will ultimately depend on whether the industry can maintain sound risk management while continuing to finance economic activity.
Customers should not interpret the capital-raising announcement as a reason to assume that every bank has the same financial position. Individual institutions differ in their business models, capital structures, loan portfolios, liquidity positions and exposure to particular sectors.
Anyone considering a banking or investment decision should therefore distinguish between industry-wide announcements and the published financial results of a specific institution. Investors should review official disclosures, while customers should continue to use regulated institutions and understand the terms of the financial products they select.
The CBN’s role will remain important as banks demonstrate compliance with the revised requirements and work to maintain adequate capital over time. Meeting a minimum capital threshold is not a substitute for effective supervision, transparent reporting, responsible lending or strong corporate governance.
The regulator will also need to monitor emerging risks, including technology-related fraud, cyber threats, poor credit decisions and changes in the economic environment that could affect borrowers’ ability to repay.
For the banking industry, the ₦4.65 trillion raised represents a substantial pool of fresh capital, but its long-term value will be judged by more than the amount collected. Investors will watch earnings and returns, businesses will look for access to suitable credit, and customers will continue to judge banks by the safety, reliability and cost of their services.
The disclosure marks an important point in Nigeria’s effort to strengthen its banking sector. The more difficult task now is to convert the stronger capital base into sustainable lending, improved financial services and greater capacity to withstand future economic shocks.
As the industry moves beyond the capital-raising phase, attention is likely to shift towards compliance, lending performance, profitability and the contribution of banks to productive economic activity.
For Nigeria, the central question is no longer simply how much capital banks have raised. It is whether that capital will help create a banking system capable of supporting businesses, protecting depositors and financing long-term economic growth without compromising financial stability.