|
Getting your Trinity Audio player ready...
|
From Promises to Pipelines: Nigeria’s Upstream and Gas Investment Boom Gets Its Reality Check
For fifteen years, Nigeria has described its natural gas as the great unrealized prize of its energy sector. The country sits on 215 trillion cubic feet of it, more than any other nation in Africa, yet output barely budged for a decade and several giant export plants stayed stuck on drawings. In the past two years, that story has started to change, with real money, real approvals and real deadlines, though the biggest tests are still ahead.
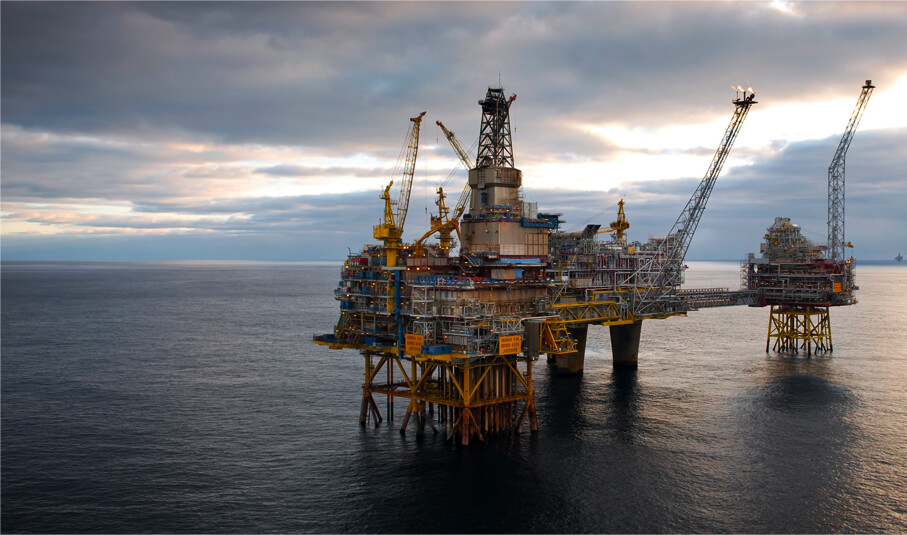
Start with the upstream picture. A government-backed review of the 2023 to 2026 reform period found that Nigeria raised its share of Africa’s upstream final investment decisions from roughly 4 percent in the previous decade to about 40 percent over the last two years. The reforms behind that jump included tax incentives aimed at deepwater developments, clearer lines between the country’s energy agencies, and a campaign to cut contracting timelines from 36 months to as little as six. The headline deals include Shell’s $5 billion Bonga North deepwater project, approved in December 2024, which involves drilling and completing 16 wells and modifying the existing Bonga Main floating production vessel, along with TotalEnergies and NNPC’s decision to develop the Ubeta gas field. The review also pointed to an estimated $50 billion pipeline of upstream projects stretching beyond 2026, including Bonga South West, Owowo, Usan and Erha. Altogether, officials say upstream commitments through final investment decisions have topped $8 billion since President Bola Tinubu took office in 2023.
Gas has now moved to the front of that queue. Speaking at a news conference in Abuja on October 2, Minister of State for Petroleum Resources (Gas) Ekperikpe Ekpo said four major gas projects have reached final investment decision, together representing about $3.5 billion of committed capital. He listed them one by one: the Iseni project at roughly $122 million, the Ubeta project at about $566 million, Shell’s HI project at $2 billion, and the Ima project at $800 million. Nigeria’s gas production, he said, has climbed from 6.86 billion cubic feet a day in 2023 to 7.5 billion today, with a target of reaching 10 billion cubic feet a day by 2027 and a broader goal of drawing $30 billion into the gas sector by 2030.
The most recent of those approvals shows how the pieces are meant to fit together. TotalEnergies, as operator with a 40 percent stake, and AMNI International, holding 60 percent, took an $800 million decision to develop the Ima field, a discovery dating back to 1973 in the OML 112 and 117 area near Bonny. The project is designed around a single platform and a 22-kilometre pipeline to the Nigeria LNG plant, delivering roughly 350 million standard cubic feet a day from 2028. That volume would cover about a third of the gas needed for Train 7, the expansion that will lift the Bonny Island plant’s capacity from 22 million tonnes a year to about 30 million. Ekpo said Train 7 should be complete by June 2027, and independent tracking showed the project about 92 percent finished as of May. Ubeta and HI together can supply up to 15 percent of the plant’s total feedgas requirements, and officials describe the pairing as the supply guarantee that makes the expansion workable.
Existing capacity is already running harder. Ekpo said Nigeria LNG’s utilisation has climbed from 59 percent to about 87 percent so far in 2026, a sign that feedgas problems that long throttled the plant have eased. Next in line is a floating LNG project from UTM Offshore, valued at around $3 billion with 1.8 million tonnes a year of capacity, which moved closer to a final decision after a 15-year gas supply agreement with NNPC and Seplat Energy was signed in July. On the domestic side, the National Economic Council approved about ₦185 billion to settle validated legacy debts owed to upstream gas producers, and Ekpo reported progress on the $3.5 billion Brass Methanol project after a dispute over its gas sales agreement was resolved.
Still, the track record deserves a sober look. Industry analysts remind readers that Nigeria’s gas output hovered at just 7.41 billion cubic feet a day in 2025, fifteen years after the country first announced its big gas ambitions. Of four large LNG plants proposed over that period, Brass LNG, Olokola LNG, West Niger Delta LNG and Trains 6 and 7 at Nigeria LNG, only Train 6 has been completed, and Train 7 has been both delayed and scaled back. NLNG itself said in 2023 that a Train 8 was no longer possible because of gas supply constraints. The energy transition has also shrunk the pool of lenders willing to back long-lived fossil fuel assets, while many Nigerian firms that bought assets from departing international oil companies lack the balance sheets to fund very large gas projects alone. Gas-to-power financing is harder still, with no major project reaching a final decision since Azura-Edo in 2016. NNPC’s latest Gas Master Plan, published in January, revived the long-stalled Olokola LNG scheme in Ogun State with a goal of reaching a final decision within twelve months, which explains this month’s talks between Ogun’s government and NNPC officials.
There’s one more pressure point the minister raised pointedly. Deep offshore producers are legally required to satisfy their domestic gas obligations before exporting, and Ekpo said the upstream regulator has the job of enforcing that rule, a reminder that Nigeria’s factories and power plants, not just its export terminals, are supposed to benefit from the new gas.
For readers trying to separate momentum from mirage, the next eighteen months will say a lot. If Train 7 starts up on schedule in 2027, Ima begins flowing in 2028, and output nears 10 billion cubic feet a day, the investment story will look like delivery rather than promise. If dates slip again, the sector’s critics will have another chapter to add to a very long book.